

Displaying items by tag: crude
How the 2026 Oil War is Dismantling Marine Supplies

How the 2026 Oil War is Dismantling Marine Supplies
Most of us only notice cargo ships when packages are late or food prices spike. But the "hidden engine room" of the global economy is currently on fire.
What was a theoretical worry became a brutal reality on March 8, 2026, when Brent crude surged past $100, eventually peaking at $126 per barrel. While headlines focus on the US-Iran conflict, the real disaster is happening in the water: the Strait of Hormuz, the world’s most vital maritime "throat", has stopped functioning.
When that happens, the questions shift from politics to survival: What do you do when your fuel costs double in a single week? How does a ship keep running when the port it relies on for spare parts is suddenly a war zone?
This is a look at how a $10.1 billion industry is being dismantled in real-time. In this article, we will cover:
- The Fuel Crisis: Why bunker fuel prices have gone vertical.
- The Insurance Blackout: Why ships are grounded even when the water is clear.
- The Spare Parts Trap: How blocked routes are leading to engine failures.
- The Future: Three scenarios that will determine if global trade survives.
Why Marine Supplies Are So Exposed to the Oil War
To get an idea of the scale of destruction, one has to look closer at the share of oil in a ship. Although many people perceive a ship as a transport means, it is much more than that. A vessel can be regarded as a self-sufficient industrial city that requires constant supply of energy and spare parts.
Of course, oil products are needed to power its engines.
Many components of a vessel (e.g., pistons and valves) are made using steel and aluminum.
Logistics, which deliver these parts from warehouses to ships, are based on oil.
In 2025, the global marine spares and equipment industry had generated revenues worth of $10.1 billion, having grown 5.1% in comparison to the previous year. All this stability is now lost. Oil isn't just one factor in this industry; it is the fundamental "DNA" of every single operation.
Bunker Fuel Goes From Commodity to Crisis
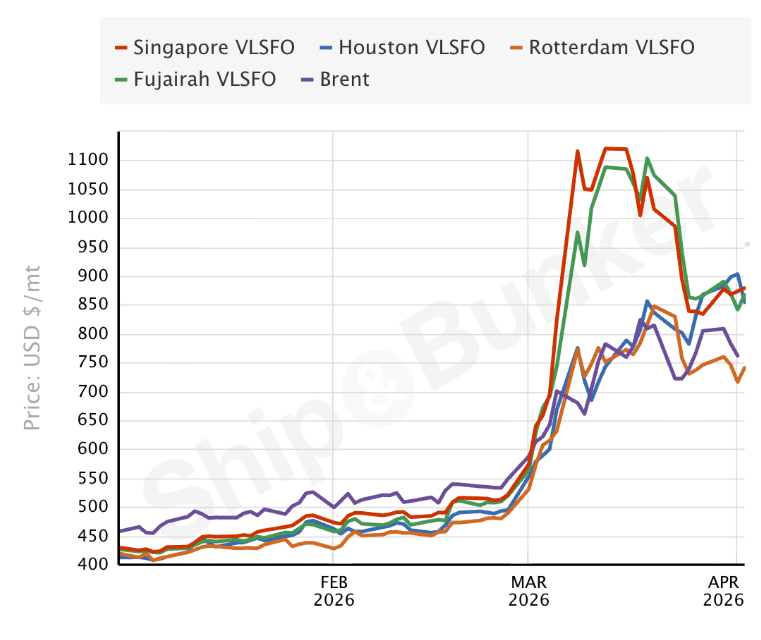
The main component of marine fuels is bunker fuel (Very Low Sulphur Fuel Oil, VLSFO). It accounts for 50% of overall costs of operating a ship. During the recent crisis, VLSFO's price has experienced a vertical growth.
According to Ship and Bunker statistics, VLSFO rate increased by 87% worldwide. Within two months, its price increased from $544 per tonne in late February to $1,125.50 in late March (the record price since the start of Russia-Ukraine War). The dynamics was as follows:
- High Sulphur Fuel Oil (HSFO): Increased its price by 112%, reaching the record high of $886 per tonne.
- Marine Gas Oil (MGO): The most sensitive part of the industry. The prices for MGO have risen by 160% since the beginning of the conflict.
In this regard, Constantinos Capetanakis, Chairman of the International Bunker Industry Association, said: "It's absolutely unprecedented."
The geography of this crisis made things even worse. First of all, one of the largest bunkering centers (Fujairah) was practically out of use after the attacks. Meanwhile, even such giant as Singapore, the largest fueling harbor, recorded the price increase of 106%.
As Maersk CCO put it, "Fuel remains available worldwide, but it is unevenly distributed." This imbalance is a direct consequence of the war.
When Carriers Start Charging Everyone More
Since the shipping companies have to deal with the rising costs, they pass them to consumers. This is where common people experience the consequences of the war, at a grocery shop or at work.
When VLCC supertanker's rate reached $423,736 per day (which is a 94% increase in just 48 hours), they decided to implement surcharges:
- Hapag-Lloyd: Added $160 per TEU in case of dry cargo.
- CMA CGM: Introduced peak surcharge worth of $400 per TEU and separate "Emergency Conflict Surcharge" of up to $3,000 per TEU in case of shipments to Gulf countries.
- Maersk & Seaboard Marine: Started to charge their clients via rolling bunker surcharges starting from late March.
One Indian shipper told S&P Global the situation is so bad that "shippers are not sending any cargo." When the cargo stops moving, the marine supplies stop moving too. It’s a total freeze of the system.
When Insurance Companies Simply Walk Away
As already noted above, marine insurance plays an extremely important role for the operation of ships. In case of absence of War Risk Insurance, vessel owners will bear all expenses related to the loss of property (about $100 mln, typically).
As soon as the conflict erupted, 21 commercial ships got under fire from Iran. In response, major insurers such as Gard, Skuld, and North Standard refused to provide coverage to ships in Persian Gulf area. For those willing to get War Risk Insurance, it becomes rather costly affair:
Peacetime insurance premium: 0.125% – 0.25% of ship's price.
Currently: 0.8% – 1.5%, with US/Israeli vessels insured for 10% or higher.
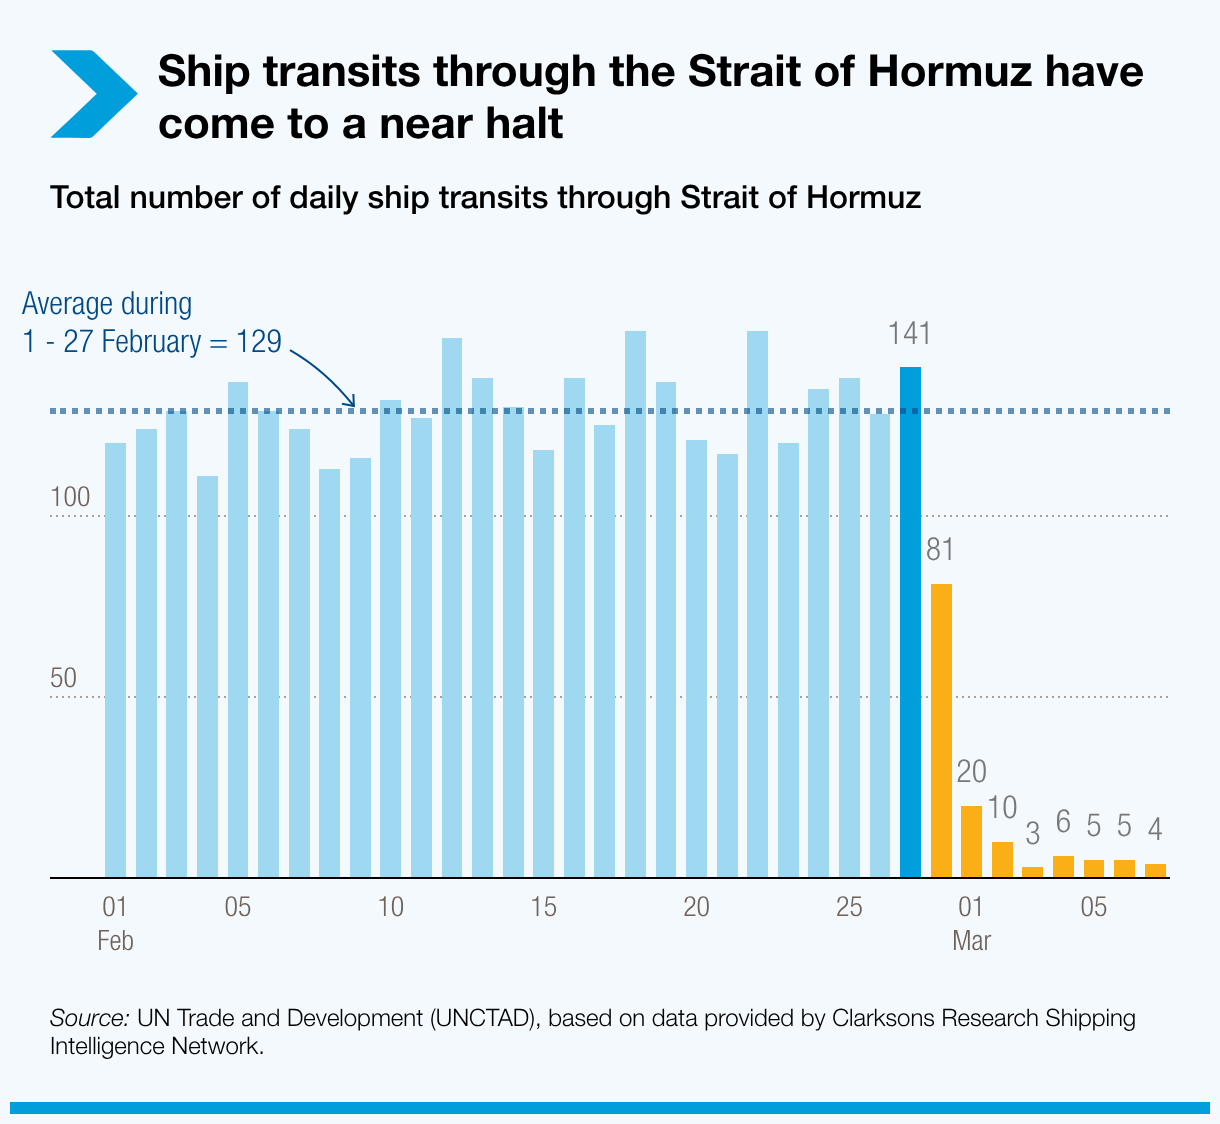
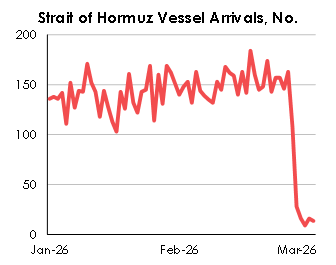
It resulted in a dramatic decrease in transit through the Strait of Hormuz. According to Clarksons Research, currently, only 13 ships managed to pass this waterway in a single week while under normal conditions 250 ships should have gone through. That equals to 95% decline in transit.
|
Peacetime premium 0.125% of vessel value per voyage
|
Crisis premium 0.8–2.5% for standard tonnage
|
US/Israeli-nexus vessels >10% per transit, where available
|
Hormuz transits — latest week 13 vs. ~250 normally (⇩ 95%)
|
What’s Happening to Spare Parts and Ship Maintenance
Of course, fuel is the most obvious aspect of crisis, but the worst may come later. As a matter of fact, the death blow could be delivered by breakdown of spare parts logistics. As mentioned before, ships need regular replacement of parts, which is possible because of four "pillars": Singapore, Rotterdam, Houston, and Fujairah/Dubai.
Now one of them is damaged due to military operations against Iran. As a result, by mid-March almost 1,000 tankers (22% of the global fleet) remain idle in the Persian Gulf.
This results in several negative effects:
- Stockpiling: The owners try to stockpile spares, buying them 30 days in advance, instead of 10. It, of course, affects storage capacity.
- "Cape" Effect: Tankers avoiding Persian Gulf are taking a longer route through Cape of Good Hope. This results in extra wear and tear.
- Deferred Maintenance: This effect can be extremely dangerous. Because spares are either delayed or become prohibitively expensive, the owners postpone their replacement. At some point, deferred repairs cause catastrophic damage to engines.
How Much Worse Could It Get?
As can be seen, the situation is dire at the moment. However, it is still not the worst-case scenario.
The disruption is also spreading beyond oil. LNG markets are now under stress, with tanker rates surging by 40% in a single day after Qatar halted production. The Strait of Hormuz typically handles around one-fifth of global LNG supply, and unlike oil, LNG has limited strategic reserves to cushion disruptions.
According to analysts, the situation is expected to worsen by mid-April. This is when the oil supplies held in the Strategic Petroleum Reserve and the oil supplies currently being allowed to flow due to sanctions are expected to exhaust themselves.
At the same time, geopolitical dynamics are evolving. In later March, Iran allowed selective transit access for ships from China, Russia, India, Iraq, and Pakistan, with Malaysia and Thailand. While this provides limited relief, it also fragments global trade flows and creates unequal access to critical routes.
According to the Kuwait Petroleum Corp.'s CEO, Sheikh Nawaf al-Sabhis, the situation could take three to four months to return to normal even after the conflict is resolved.
This means the situation is here to stay and could set a new standard in the costs of oil and shipping.

There are three possible scenarios which could play out in the near future.
Scenario 1:
If the Strait of Hormuz opens up by mid-April, the prices of bunker oil could fall to between $700 and $800 a tonne. Emergency surcharges could begin to fall off. Logistical issues with spare parts could return to normal. However, the prices of insurance could continue to be high, and the backlog of repairs could take months to resolve.
Scenario 2:
If the situation continues into the second half of the year, the situation would become more severe.
This is because the Philippines has already declared a national energy emergency and depends on the Gulf for 98% of its oil supplies.
The global economic impact is already visible. According to Bloomberg Economics, US CPI rose to 3.4% year-on-year in March, up from 2.4% in February, largely driven by rising fuel costs.
At the same time, more than 44,000 businesses across 174 economies have already had at least one shipment exposed to disruption, highlighting the global reach of the crisis.
UNCTAD has warned of a situation where the costs of foodstuffs, manufacturing, and shipping could escalate due to the prolonged blockage of Strait of Hormuz. Developing countries would be the hardest hit.
At the same time, Singapore's bunker reserves would start to deplete. The reserves are currently maintained through low demand because of high prices. Nevertheless, when the reserves get to a critical level, even the largest bunkering centers would face a problem. This would disrupt the entire network.
Scenario 3:
Should the conflict spread further, affecting Saudi Arabia's oil installations such as Ras Tanura oil terminal, it would result in an unprecedented increase of the prices: $150-$200. In this case, the concept of affordable global shipping would become extinct. The shipping industry simply cannot withstand such price levels.
How the Industry Is Coping
The shipping industry finds itself in survival mode. To cope with it, following measures have been taken so far:
- Maersk is diverting fuel from costlier alternative sources and "slow steaming" (driving ships slower) to save oil. While this saves money, it increases transit times, making everything you buy take longer to arrive.
- The other option is the change in international regulations.
- Industry-wide shift to 30-day fuel procurement advance ordering, up from 10 days has become popular among ship owners.
- Ships have started Stockpiling of critical spares and diversification away from Middle East logistics hubs
- The International Maritime Organization held a special session with the purpose of discussing how to overcome this crisis strategically.
- Additionally, there are talks about transferring the center of gravity of the industry from Houston and Dubai toward Rotterdam and Singapore. However, moving a supertanker requires time.
Conclusion
Today, the marine supplies industry is facing a perfect storm. Previously, similar issues occurred in a localized manner, which meant partial destruction of certain links in the chain. In contrast to this, today, every aspect (fuel, insurance, spare parts and maintenance, routes) is affected. The human price of these changes is rather high. World Food Programme (WFP) warns that the threat of extreme hunger in Africa and Asia could rise to 17-25%, correspondingly.
Also, according to Dallas Federal Reserve research, losing 25% of Hormuz transit could cause global GDP shrinkage to 2.9%. This happens because the shipping process, spare parts delivery, and fuel supply are interrelated. If one link breaks, all others will suffer. Currently, every link in this chain is in dire straits. By mid-April we will see whether they will survive.
Written by: Saman Ali
Disclaimer:
This article is for informational and educational purposes only and does not constitute financial, investment, trading, or legal advice. Always do your own research or consult a licensed advisor before making trading decisions.
Gold, Silver & WTI: Macro Drivers, Geopolitics and Trading Playbook (2025 Outlook)

Gold, Silver & WTI: Macro Drivers, Geopolitics and Trading Playbook (2025 Outlook)
1. Executive Summary
Over the past few years, gold, silver and U.S. crude oil (WTI) have traded through one of the most volatile macro regimes in decades: a pandemic shock, aggressive monetary tightening, persistent inflation, and overlapping wars.
-
Gold has surged to around $4,100–4,200/oz, more than doubling from pre-pandemic levels, lifting its estimated market capitalization to roughly $30 trillion in 2025.
-
Silver has outperformed gold in percentage terms, climbing from about $20/oz in late 2023 to above $50/oz in late 2025, driven by industrial demand (especially solar) and a structural supply deficit.
-
WTI crude oil is currently trading just below $60/barrel, down from its post-pandemic spikes above $100, as supply growth and the prospect of peace in Ukraine weigh on prices.
For online traders, these three markets offer a powerful mix of liquidity, volatility and macro sensitivity. But they are also heavily driven by world economic data, geopolitics, wars, and central banks, and must be approached with a clear framework.
2. How We Got Here: 2020–2025 in a Nutshell
Pandemic, Money Printing and Inflation
From 2020 onwards, global markets went through three distinct phases:
-
Shock (2020) – COVID-19 crushed demand, sending WTI briefly negative on futures expiry and driving an historic collapse in oil prices, while gold and silver initially sold off in the global liquidity scramble.
-
Liquidity Wave (2020–2021) – Massive fiscal stimulus and ultra-low interest rates pushed real yields deeply negative. Gold and silver rallied as “monetary assets”, while oil rebounded as demand slowly normalised.
-
Inflation & Rate Hikes (2021–2023) – Inflation surged to multi-decade highs in many economies. Central banks, led by the Fed, embarked on the most aggressive hiking cycle since the 1980s. Real yields rose, temporarily capping gold and silver, but energy markets stayed volatile due to supply constraints and war.
Wars and Geopolitics
Two major shocks reshaped commodities:
-
Russia–Ukraine war (from 2022):
-
Tightened energy markets via sanctions and supply disruptions, pushing oil and gas sharply higher initially.
-
Raised risk premia across safe-haven assets, including gold.
-
-
Broader Middle East tensions and proxy conflicts:
-
Periodically boosted oil risk premiums and safe-haven flows into gold.
-
Increased demand for “crisis hedges” among institutional and retail traders.
-
By late 2025, markets are transitioning into a phase where growth is slowing, inflation remains above central bank targets, and traders are increasingly pricing future rate cuts, a combination that tends to favour precious metals while limiting upside in oil if supply remains ample.
3. How Economic News and Geopolitics Move Gold, Silver and Oil
3.1 Interest Rates, Real Yields and the U.S. Dollar
The single most important macro driver for gold and silver is the interaction between:
-
Nominal yields (e.g. U.S. 10-year Treasury);
-
Inflation expectations;
-
The U.S. dollar (DXY).
Higher real yields and a stronger USD usually weigh on gold and silver, as the opportunity cost of holding non-yielding metals rises. Conversely, when markets price rate cuts or expect inflation to stay sticky, real yields fall and precious metals typically gain.
WTI is also sensitive to the dollar (a stronger USD tends to pressure commodities priced in dollars), but demand growth, inventories and OPEC+ policy usually dominate.
3.2 Growth Data and Inflation Releases
Key data releases that move XAUUSD, XAGUSD and USOIL CFDs include:
-
U.S. CPI & PCE inflation – surprise upside boosts inflation hedging demand for gold/silver; downside surprises can hurt them if they imply more dovish inflation risk.
-
Non-Farm Payrolls (NFP) and unemployment – strong labour data can lift yields and the dollar, often pressuring precious metals and supporting oil via growth expectations.
-
PMIs / ISM data – indicate manufacturing and services momentum, impacting industrial demand for silver and fuel demand for oil.
3.3 Wars, Sanctions and OPEC+
Geopolitics channels into prices via:
-
Actual supply disruptions: pipelines, shipping routes, sanctions, OPEC+ cuts/boosts.
-
Risk premia: even without physical disruption, traders price in the probability of escalation.
For oil, OPEC+ meetings, announcements on quotas and unplanned outages are core catalysts. For gold and silver, headline risk around escalation, sanctions or financial instability tends to drive short-term spikes as traders rush into safe-haven trades.
4. Gold: The Monetary Metal and Crisis Asset
4.1 Price Performance and Market Size
-
Spot gold is trading around $4,100–4,200/oz in late November 2025, near record highs.
-
Over the last decade, gold has more than tripled in many major currencies.
-
Estimated market capitalization of above-ground gold is roughly $29–30 trillion, dwarfing individual equities and even Bitcoin.
This scale matters: gold is effectively a parallel monetary system. Central banks, sovereign funds, hedge funds and retail investors all participate, making gold one of the deepest and most liquid markets online traders can access through XAUUSD CFDs, spot and futures.

4.2 Why Gold Prices Have Risen
Key reasons behind gold’s multi-year bull trend:
-
Negative real yields through much of 2020–2022.
-
Central-bank buying – many EM central banks increased gold holdings to diversify away from the U.S. dollar.
-
Inflation and fiscal dominance fears – ballooning government debt and concerns about long-term currency debasement.
-
Geopolitical fragmentation – sanctions and financial de-risking have made gold more attractive as an asset outside the dollar system.
4.3 What Traders Should Watch for Gold
Key drivers for XAUUSD:
-
U.S. real yields (10-year TIPS) – downtrend is bullish; a sharp spike higher is a clear warning sign for longs.
-
DXY – a structurally weaker dollar supports the gold bull case.
-
Central bank communication (FOMC, ECB, BoE, etc.) – dovish pivots usually support gold.
-
Systemic risk headlines – banking stress, sovereign debt issues, war escalation.
5. Silver: The Hybrid Metal – Monetary Plus Industrial
5.1 Performance and Market Size
-
Silver is trading in the low-to-mid $50s/oz in late November 2025, having risen around 160% from about $20.7 in October 2023 at its recent peak.
-
Its market capitalization is estimated just above $3 trillion, an order of magnitude smaller than gold, which helps explain silver’s higher volatility.

5.2 Structural Supply Deficit and Solar Boom
Silver’s rally is not only about monetary hedging:
-
Industrial demand – particularly from solar PV, electronics and EVs – has surged. Solar alone accounted for nearly a quarter of silver’s industrial demand in 2024, up sharply since 2020.
-
Persistent supply deficits – several recent market studies project continued silver market deficits, with 2025 expected to mark the fifth consecutive year of significant shortfalls.
At the same time, silver is largely mined as a by-product of other metals, making supply less responsive to price spikes.
5.3 What Traders Should Watch for Silver
For XAGUSD traders, silver is a high-beta play on:
-
All the monetary drivers of gold (real yields, USD, inflation expectations);
-
Plus industrial cycle indicators – global manufacturing PMIs, semiconductor cycles, and solar installation forecasts.
Because of its smaller market cap and industrial component, silver often outperforms gold in bull markets and underperforms in sharp risk-off shocks. That makes it attractive for short-term momentum traders but dangerous for over-leveraged positions.
6. WTI Crude Oil: The Macro Growth and Geopolitics Barometer
6.1 Price Context
-
WTI is hovering around $58–59/barrel in late November 2025, after a multi-month decline driven by rising supply and easing risk premia
-
Major banks (e.g. JPMorgan) now project mid-$50s WTI by 2027, highlighting a base case of balanced but well-supplied markets

6.2 Key Drivers
-
Global demand – tied to GDP growth, particularly in the U.S., China and emerging Asia.
-
Supply from OPEC+ and U.S. shale – production cuts or increases, reserve policy, capital discipline.
-
Wars and sanctions – Russia, Middle East, shipping disruptions (e.g. Straits, canals).
-
Energy transition – long-term headwind on demand growth, but also under-investment in fossil fuels can create supply squeezes in the medium term.
For CFD traders in USOIL/WTI, this market is ultra-liquid, with deep futures volume on CME and ICE, making it ideal for short-term trading but also very sensitive to intraday headlines.
7. How These Markets Tie Into Inflation
-
Energy is a direct input into CPI via fuel, transport and production costs. Spikes in WTI quickly feed through to headline inflation.
-
Gold and silver act primarily as inflation hedges via expectations:
-
When investors believe inflation will remain above target or that central banks are behind the curve, they move into precious metals.
-
When inflation appears tamed and central banks are credible, demand for hedges can fade.
-
In the last few years, both actual inflation and inflation uncertainty have risen. That’s why we’ve seen a regime where energy shocks and monetary expansion reinforced each other, supporting both gold/silver and oil at various points.
8. Forward-Looking Price Zones and Scenarios
(Not investment advice – indicative ranges for scenario planning.)
Given current macro conditions (late 2025), traders are broadly focused on these zones for the next 6–18 months:
8.1 Gold (XAUUSD)
With spot near $4,100–4,200/oz and a recent peak around $4,380, traders watch:
-
Bullish extension:
-
Break and weekly close above $4,400–4,500 could open $4,800–5,000 as an extended target if real yields fall and rate cuts accelerate.
-
-
Base case range:
-
Consolidation between $3,600 and $4,400 as markets transition into a slower-growth, lower-rate regime.
-
-
Bearish scenario:
-
A strong disinflation surprise plus higher real yields could drag gold towards $3,200–3,400, where long-term trend support likely attracts large buyers.
-
8.2 Silver (XAGUSD)
With silver around $50–54/oz after a parabolic move:
-
Bullish extension:
-
A sustained break above the recent peak (~$54+) could target $60–65, especially if solar demand accelerates and deficits deepen.
-
-
Base case:
-
A volatile trading range between $40 and $55, with sharp swings around data and risk sentiment.
-
-
Bearish scenario:
-
A cyclical slowdown in industry and a broad risk-off could push silver back towards $35–38, or even the high-20s in an extreme liquidity shock.
-
8.3 WTI Crude Oil (USOIL)
With WTI near $58–59 and forecasts clustering around the mid-50s long term:
-
Bullish extension:
-
Renewed supply shocks (war escalation, OPEC+ cuts, sanctions) could push WTI into a $75–85 band.
-
-
Base case:
-
A broad $50–70 range, as non-OPEC supply growth and moderate global demand keep the market balanced.
-
-
Bearish scenario:
-
A hard global landing and/or peace-driven surge in Russian exports could force oil into the $40–50 range.
-
These are scenario-based levels, not guarantees. They give online traders reference zones for building trade ideas and risk/reward profiles.
9. Why Traders Should Trade These Markets (Online/CFD Context)
From an online trading perspective, XAUUSD, XAGUSD and USOIL offer:
-
High liquidity & tight spreads – ideal for intraday and swing strategies.
-
Clear macro narratives – easier to anchor trade ideas to economic releases and geopolitical events.
-
Diversification – they behave differently from major FX pairs or indices, especially during crises.
-
Hedging – portfolio managers and active traders can hedge equity or currency exposure via metals and energy.
For your audience (retail CFD and spot traders), the attraction is that all three can be traded long or short with leverage, around the clock, from a single trading platform. The risk, of course, is that leverage magnifies both gains and losses.

10. When to Enter: Practical Trading Approaches
10.1 Trend-Following with Pullbacks
-
Identify the dominant trend on daily/weekly charts:
-
Gold and silver are currently in structural uptrends.
-
WTI is in a medium-term downtrend / wide range.
-
-
Use pullbacks to key moving averages or prior breakout zones (e.g. 50/100-day MA, previous highs/lows) to time entries in the direction of the trend.
-
Combine with momentum indicators (RSI/MACD) to avoid chasing overextended moves.
10.2 Event-Driven Trading Around News
Some traders specialise in trading CPI, NFP, FOMC and OPEC meetings:
-
Before the event: volatility premium rises, spreads may widen; position sizes should be reduced.
-
After the event: if price action confirms the macro signal (e.g. dovish Fed + gold breakout), traders can enter with tighter invalidation levels.
10.3 Mean-Reversion at Extremes
Because metals and oil often overshoot:
-
Watch for false breakouts (break above resistance that quickly reverses) with high volume.
-
Use oscillators and positioning data (COT reports, futures positioning) to identify crowded trades.
This is particularly relevant for silver, which frequently overshoots gold’s move in both directions.
11. What Traders Should Be Paying Attention To (Checklist)
For a practical “trader’s dashboard”:
Macro & Central Banks
-
Fed rate decisions, dot plots and press conferences
-
U.S. CPI, PCE, NFP, ISM/PMI
-
ECB, BoE, BoJ policy shifts
Market Indicators
-
U.S. 10-year yield and real (TIPS) yield
-
DXY (U.S. dollar index)
-
Gold–Silver ratio (risk sentiment within metals)
Geopolitics & Energy
-
Russia–Ukraine peace negotiations, sanctions updates
-
Middle East headlines and shipping disruptions
-
OPEC+ meetings and quota announcements
Sector-Specific
-
For gold: central-bank gold purchases, ETF flows
-
For silver: solar/green energy policy, industrial demand forecasts, supply deficit reports
-
For oil: U.S. inventory data (EIA), rig counts, Chinese demand data
Risk Management (especially for CFDs)
-
Use stop-losses beyond obvious intraday noise.
-
Scale position size to volatility: silver and USOIL often justify smaller sizes than XAUUSD.
-
Avoid being over-leveraged going into tier-1 data releases.
12. Final Thoughts
Gold, silver and WTI sit at the intersection of macro, geopolitics and market psychology. Over the last few years, they’ve responded aggressively to money printing, inflation, wars and shifting expectations about growth and interest rates.
For online traders, these instruments are not just “charts to trade” but expressions of big global narratives. The edge comes from:
-
Understanding which narrative is currently in control;
-
Aligning your trades with that narrative;
-
Managing leverage and risk with discipline.
Disclaimer:
This article is for informational and educational purposes only and does not constitute financial, investment, trading, or legal advice. Always do your own research or consult a licensed advisor before making trading decisions.


