

Displaying items by tag: microsoft
Big Tech Q1 2026 Earnings: AI Winners, Losers & Nvidia Outlook

Big Tech Just Had Its Best Quarter in Years. So Why Is the Market Still Nervous?
What happens when the biggest problem facing tech stocks is not poor earnings... but impossible expectations?
That is the true story of Q1 2026 earnings season.
On the surface, tech stocks just delivered one of their best earnings reports in recent memory. But beneath the headlines, something even more interesting is occurring: artificial intelligence is driving a huge divide within the tech sector itself. Some stocks are about to enter an accelerated growth cycle. Other stocks are quietly being left behind.
And now, with Nvidia set to report earnings tonight, we're finally going to see if the bull run in artificial intelligence can keep going... or whether the tech market has become too optimistic about its future growth.
If you're invested in tech stocks right now, then this is the earnings briefing you need.
The Earnings Season That Changed Wall Street's Expectations
The numbers were astounding.
Despite more than 90% of S&P 500 companies having already reported Q1 2026 earnings, profit growth is currently tracking to near 27% growth year over year – double what Wall Street expected heading into earnings season.
That means this has been the best quarterly earnings growth period since 2021.
And with roughly 83% of S&P 500 companies having beaten their forecasts this quarter, that number has actually been even higher than usual.
Then why is the market still nervous?
Because earnings beats do not matter.
Investors no longer want just good results. They want perfection.
S&P 500 companies which missed expectations have fallen short of market indices by almost 5% in the day following earnings. By contrast, companies which beat estimates managed only a modest 1% gain.
Why?
Because strong earnings are already baked in.
The market is now assuming AI-driven growth will continue accelerating.
And that makes the next few days very important.
The Big Tech Earnings Scorecard: Who Really Won?
The most intense earnings battle took place the week of April 29th, when Microsoft, Alphabet, Amazon, and Meta all released earnings on consecutive days before Apple did on the fifth.
But despite all of them having performed well in terms of earnings growth, not all big tech stocks impressed investors.
|
Metric |
Alphabet |
Amazon |
Microsoft |
Apple |
Meta |
|
Q1 2026 Revenue |
$109.9B |
$181.5B |
$82.9B |
$111.2B |
$56.31B |
|
Revenue Growth YoY |
+22% |
+17% |
+18% |
+17% |
+33% |
|
Core AI / Cloud Segment |
Google Cloud |
AWS |
Azure |
Services Ecosystem |
AI Advertising & Infrastructure |
|
AI / Cloud Growth |
Google Cloud +63% |
AWS +28% |
Azure +40% |
Services margins ~77% |
Ad revenue + AI monetization acceleration |
|
Earnings Highlight |
Net income +81% |
EPS nearly doubled estimates |
AI business ARR reached $37B |
EPS +22%, China sales +28% |
Daily active users hit 3.58B |
|
AI Infrastructure Spending |
2026 capex guide: $180B–$190B |
Planning over $200B capex |
Projected ~$190B capex |
Roughly $13B annual capex |
$115B–$135B AI capex guide |
|
Investor Reaction |
Biggest winner of earnings season |
Positive but underhyped |
Strong results but muted reaction |
Investors split on AI positioning |
Stock dropped nearly 7% post-earnings |
|
Biggest Investor Concern |
Rising AI spending intensity |
Can margins hold during massive expansion? |
OpenAI exclusivity ending |
Is Apple falling behind in AI? |
Spending rising faster than monetization |
|
Main Bullish Thesis |
Fastest-growing hyperscaler with huge AI backlog |
AWS becoming backbone of AI infrastructure |
Enterprise AI dominance |
Massive profitability with low capex |
Unmatched scale for AI-driven advertising |
|
Key Market Narrative |
AI strategy clearly working |
Quiet AI infrastructure giant |
Great results no longer enough |
Efficiency vs AI race debate |
Market demanding faster AI returns |
1- Alphabet was the Clear Winner
Alphabet delivered one of the strongest quarters of the bunch.
Its Google Cloud business generated a remarkable 63% year-over-year growth to $20 billion, which accelerates dramatically from 48% growth in Q4 2025, and now makes Google Cloud the fastest-growing hyperscaler in this cycle.
Why?
Because Alphabet proved yet again that its entire AI strategy is working.
From custom AI chips to an ever-growing backlog of orders, a strong search engine ad market, to cloud acceleration, everything is pointing to one thing:
Alphabet becoming one of the leading AI infrastructure companies on Earth.
And investors can tell.
2- Amazon Quietly Built an AI Advantage of its Own
AWS growth soared by 28% year over year to $37.6 billion.
It's the strongest cloud growth Amazon has seen in 13 consecutive quarters.
Advertising revenues rose 23%.
But the real story is infrastructure.
All major AI labs use AWS computing power, while Amazon is planning to spend over $200 billion in capex in the upcoming year in anticipation of growing AI demand.
Here's the question investors need to answer now:
Could Amazon become one of the biggest AI infrastructure leaders without drawing the same investor attention as Nvidia and Microsoft?
3- Microsoft Had Excellent Results But Not Good Enough for Markets
In Q1 2026, Microsoft delivered Azure growth of 40% and total revenue of $82.9 billion.
Historically, such numbers would've generated a monumental rally.
But this time, investors responded quite tepidly.
Why?
Because Microsoft suddenly appeared somewhat underwhelming compared to Alphabet's growth in its cloud services.
Not only did Microsoft end its exclusive partnership with OpenAI, giving its competitor free access to all its frontier models until 2032, but it also made many investors question:
Is Microsoft's dominance in AI over now?
4- Apple Stock May Be the Most Exciting One to Watch in Tech This Year
Apple delivered arguably the best results of the season.
Q1 2026 saw total revenue grow 17% to $111.2 billion, and EPS jump by 22%. Greater China sales skyrocketed by 28% to $20.5 billion, and the company's services segment maintained its acceleration with gross margins staying at about 77%.
However, investors' eyes cannot stop looking at a single number:
Apple managed all of this while spending no more than $13 billion per year on capex investments.
How does that compare to Microsoft's projected $190 billion, and Amazon's $200 billion AI buildout in the year ahead?
Now investors have to decide for themselves:
Was Apple able to generate spectacular results while saving billions over its competitors' costs in AI infrastructure projects?
Or is the technology giant quietly lagging in AI development?
This question will define Apple's valuation in the coming two years.
5- Meta Revealed Investors' Biggest Fear in AI
Meta delivered excellent results once again with 33% y-o-y and $56.31 billion in revenue.
Ad growth stayed robust, while daily active users reached a staggering 3.58 billion users.
But investors ignored the positive numbers, fixating their sights on expenses.
Meta said it plans to spend between $115 billion to $135 billion building AI infrastructure next year alone.
The stock dropped almost 7% after earnings.
That move reveals something important about today's market:
Investors only reward heavy AI spending when returns rise faster than costs.
If spending is outpacing monetization, investors punish the companies involved ruthlessly.
AI Is Creating an Emerging Class of Winners and Losers Among Tech Stocks
Another trend emerging during this earnings season is the huge performance discrepancy between technology stocks.
Since the start of Q1 2026 earnings, there has been a difference of 133 percentage points between the top-performing and worst-performing stocks in technology this year.
The gap is widening. Three years ago, the discrepancy between tech stocks barely reached 75 points.
The time of AI lifting the entire industry is over. Now some companies are starting to emerge as leaders in this field.
The Winners: Tech Stocks Focused on Hardware and Semiconductors
As you would probably expect, the winners this earnings season include companies focusing on AI infrastructure development.
SanDisk shares are up a whopping 511% YTD. Intel delivered blowout Q1 results which pushed its revenue up over 225%. Seagate Technology and Western Digital have soared by roughly 194% and 183%, respectively.
VanEck Semiconductor ETF has surged by 58% YTD, too.
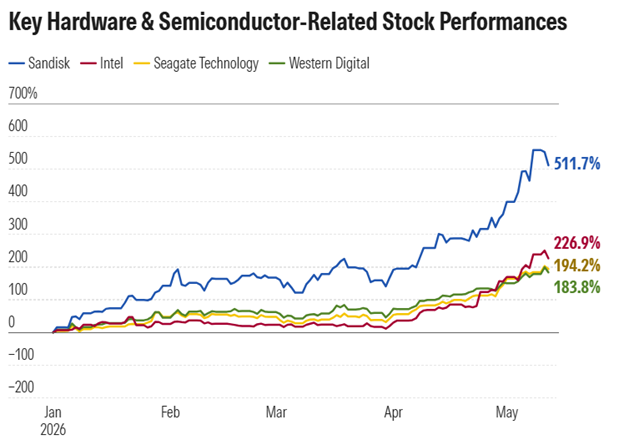
Image Source: Morningstar
Why?
Because artificial intelligence needs a lot of semiconductors, chip memory, networking, and storage solutions to process massive amounts of data.
The Losers: AI-Destroyed Software Companies
The software sector has experienced massive pain this earnings season.
Over 75% of stocks in the Morningstar US Technology Index are negative in 2026.
HubSpot's stock price is down almost 50%. Atlassian's shares are down about 47%. Workday has dropped by roughly 44%.
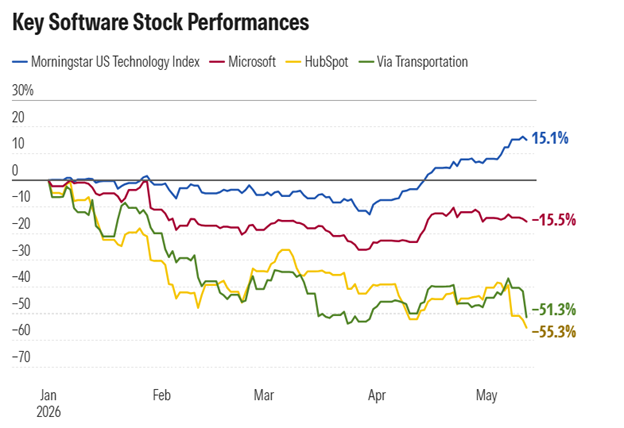
Image Source: Morningstar
Why?
Because more and more software investors are worrying about AI potentially disrupting their companies' business models.
That may end up being overly pessimistic. After all, many analysts predict that software companies will simply adapt to new technologies.
But for investors in technology stocks, that means taking a chance.
Holding a broadly-diversified tech stock ETF no longer means getting great exposure to AI innovation. Many of those indexes now contain software stocks that can significantly drag down AI's gains.
The First Phase of Artificial Intelligence IPO Boom Is Here
The next phase of the AI growth cycle is starting now with several IPOs.
Last week, Cerebras Systems debuted on Nasdaq in what's shaping up to be the biggest tech IPO since Uber's initial listing in 2019.
The company raised $5.55 billion, opening its trading at $350 per share, and closing with a 68% increase to a valuation of about $95 billion.
Cerebras builds AI-focused wafers-cale processors for inferencing purposes – the area investors worry could soon become AI's main bottleneck.
But besides signing a $20 billion cloud deal with OpenAI and a massive infrastructure contract with Amazon Web Services, the company faces competition from Nvidia, and poses real customer concentration risks.
Investors should therefore be careful.
But there's another message the market wants to send clearly:
The appetite for AI companies listed on the Nasdaq remains immense.
And the IPO pipeline ahead with Databricks, OpenAI, Anthropic, and Elon Musk's SpaceX xAI company merger, could soon provide us with the biggest wave of tech listings in years.
Nvidia Earnings Could Decide the Future of All AI-Related Stocks
The coming earnings season will hinge on Nvidia's performance.
The street predicts the tech titan will deliver adjusted EPS of about $1.77, and a revenue number of $78.9 billion for this quarter – both implying over 79% YOY growth.
But what truly caught everyone's attention is Nvidia's Q1 data center revenue, predicted to exceed $73.3 billion, which is a near 87% rise from last year.
And with analysts predicting Nvidia's FY 2027 revenues reaching almost $370 billion (about 71% growth), tonight's earnings become extremely crucial.
Why?
Because the market stopped caring about earnings misses long ago.
They assume Nvidia will beat analysts' expectations.
But tonight they'll want to see something different:
Strong guidance for future earnings driven by Nvidia's Blackwell AI chips, hyperscaler demand, and AI spending in infrastructure.
The Two Risks Facing Nvidia and All Artificial Intelligence-Linked Companies
But there are two other problems tech stocks are facing right now.
Rising bond yields and crude oil prices.
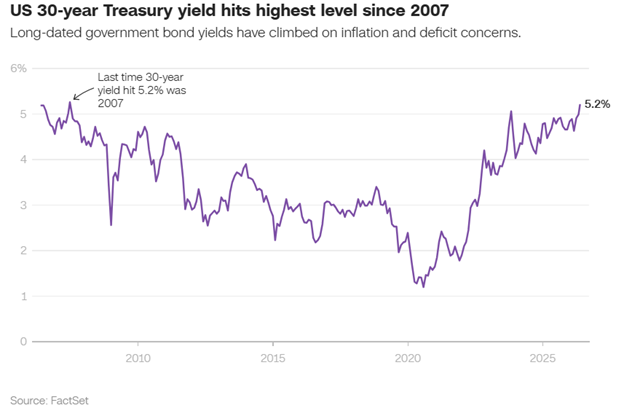
Yields on the 10-year and 30-year US Treasuries have climbed to 4.6% and 5.2%, respectively. 30-Year US treasury hit its highest level in 19 years since 2007.
Oil prices are also on the rise due to Strait of Hormuz supply issues, now pushing them above $100 per barrel. This is fuelling fears of renewed inflation and potential tightening by the Federal Reserve.
Why is this relevant?
Because rising bond yields hurt companies valued primarily on their future growth, cutting down the present value of their future cash flows.
That is why the Nasdaq fell and several stocks in Magnificent Seven declined despite posting blowout results.
That leaves two risks investors must consider while watching Nvidia's earnings:
Will the AI growth narrative remain intact for investors? And can artificial intelligence momentum offset rising bond yields?
If Nvidia's guidance for FY 2027 turns out solid and positive for investors with news on Blackwell AI chips, hyperscalers' demands, and AI infrastructure spending... Then Nvidia's decline after the report will create another buying opportunity for premium artificial intelligence stocks.
But if Nvidia fails to impress, rising bond yields can spark a much deeper correction among the entire class of AI tech stocks.
Written by: Saman Ali
Disclaimer:
This article is for informational and educational purposes only and does not constitute financial, investment, trading, or legal advice. Always do your own research or consult a licensed advisor before making trading decisions.
Q4 2025 Earnings Review: AI Leadership in Tech vs. Structural Headwinds in Energy

Q4 2025 Earnings Review: AI Leadership in Tech vs. Structural Headwinds in Energy
Tech and Energy Earnings Review Q4 2025: An in-depth study of Nvidia, Apple, Microsoft, and energy giants based on data-driven information to guide investors.

Key Insights
- Broad-based earnings strength was achieved through technology companies, which was due to continued AI and cloud investment.
- The outcome of the energy sector showed both positive and negative performance due to decreased crude prices and narrowing of the margins.
- The AI infrastructure investment remained in the process of redefining capital investment in the two sectors.
- Investors in 2026 have to deal with valuation discipline and geopolitical risk management as well.
Introduction:
With the end of Q4 2025 earnings season, investors have a better idea of how the major technology and energy companies have fared in the face of enduring geopolitical tensions, higher interest rates, and structural changes as a result of artificial intelligence.
FactSet reports that earnings of the S&P 500 increased in high single digits on a year-over-year basis. Nonetheless, there was an increase in sector dispersion. Technology was at the forefront, using AI-driven revenues, and energy companies were adapting to fluctuations in prices and regulatory risks.
This review considers the true performance in terms of earnings of the major companies and weighs their strategic impact on long-term investors.
Technology Sector Performance

NVIDIA: Continued Domination in AI Infrastructure.
Financial Highlights (Q4 FY2025):
- Revenue: $57.0B(+78% YoY)
- EPS: $0.89 (+80% YoY)
- Gross Margin: ~73%
- Data Center Revenue: $35.6B
NVIDIA has reported another record quarter, where the hyperscaler market of advanced GPUs and AI systems is in demand. Backlog orders stretched to fiscal 2026, which strengthens the revenue on a long-term basis.
Investment-wise, Nvidia is the fundamental beneficiary of the worldwide adoption of AI, but the sensitivity of valuation has been elevated.
Microsoft: Cloud and Enterprise Stability
Financial Highlights:
- Revenue: $81.3B(+18% YoY)
- EPS: $3.65 (+24% YoY)
- Net Income: $27.2B
- Azure Growth: High-teens %
The Q4 performance of Microsoft was an indication of a high use of cloud and artificial intelligence-based productivity tools by enterprises. Azure was one of the key growth drivers, and Copilot adoption increased ecosystem stickiness.
Microsoft continues to present to its investors a growth, cash-generating, and defensive stability profile.
Apple: Ecosystem Resilience
Financial Highlights:
- Revenue: $143.8B(+8% YoY)
- EPS: $1.85 (+13% YoY)
- Gross Margin: 47.2%
- Services Revenue: All-time high.
The hardware sales of Apple were still not evenly distributed in regions, especially in China. The increase in services and ecosystem monetization, however, counterbalances the cycle of devices.
The performance of Apple confirms the transition towards a recurring-revenue-based model of the business.
Intel: Gradual Recovery Phase
Financial Highlights:
- Revenue: $13.7B (–4% YoY)
- EPS: –$0.06 (GAAP)
- Gross Margin: Moving in the right direction.
- Foundry Investment: Ongoing
Intel went on with its restructuring and manufacturing rearrangement. As much as the profitability is still under pressure, better utilization rates and demand for the AI-server are giving encouragement for stabilization.
Energy Sector Performance

ExxonMobil: Cash Flow Resilience
Financial Highlights:
- Earnings: $6.5B
- EPS: $1.53
- Operating Cash Flow: $12.7B
- Free Cash Flow: $5.6B
Reduced crude prices forced margins down, but restrained capital allocation and efficiency in the upstream saved shareholders' returns.
Chevron: Operational Discipline
Financial Highlights:
- Revenue: $46.9B
- EPS: $1.52
- Cash Flow: $10.8B
The performance of Chevron pointed out the cost efficiency and strength of the balance sheet as a buffer to commodity cycles.
Shell: LNG and Trading Strength
Financial Highlights:
- Adjusted Earnings: $3.3B
- Free Cash Flow: $9.4B
- Buybacks: Continued
The Shell gas and LNG trading business operations were integrated, which added stability even when the refining margin pressure was high.
PetroChina: Policy-Driven Stability
Even though all Q4 2025 data is not available, the recent performance of PetroChina is characterized by:
- 2024 Net Profit: $23B+ (record level)
- Production Growth: +2.5% YoY
- Capital Support by the State.
The national energy administration in China is still focused on national energy security, which upholds the upstream investments and price stability of PetroChina. The volatility of earnings is mitigated by government-supported infrastructure expenditure and long-term contracts on supplies.
To the investors, PetroChina comes with a stability that is backed by policies but with little upside because of the controlled prices.
Earnings Snapshot
|
Company |
Revenue |
EPS |
YoY Trend |
Key Driver |
|
Nvidia |
$57.0B |
$1.30 |
Strong |
AI chips |
|
Microsoft |
$81.3B |
$4.14 (Non-GAAP) / $5.16 (GAAP) |
Strong |
Cloud |
|
Apple |
$143.8B |
$2.84 |
Strong |
iPhone & Services |
|
Intel |
$13.7B |
$0.15 (Non-GAAP) / –$0.12 (GAAP) |
Weak / Improving |
Restructuring |
|
ExxonMobil |
~$82.3B |
$1.53 (GAAP) / $1.71 (Adj.) |
Mixed |
Upstream |
|
Chevron |
$46.9B |
$1.52 |
Stable |
Efficiency |
|
Shell |
$64.1B |
~$1.12 (Adj.) |
Mixed |
LNG |
|
PetroChina |
~719B CNY (~$100B+ USD) |
~0.23 CNY (~$0.03 USD) |
Stable |
Policy Support |
Valuation and Downside Risks
Overvaluation Risk
The stocks of mega-cap technology have higher multiples than the historic average. There are several ways Nvidia and Microsoft are exposed to compression in case AI expenditure levels off.
China Exposure
Apple, Nvidia, and Intel are exposed to demand risk due to the export control and regulatory restrictions on China-related revenues.
Policy and Regulatory Risk
Continued lowering of Brent prices to below $60 may strain the margins of Exxon, Chevron, and Shell companies, especially in downstream operations.
Policy and Regulatory Risk
- AI governance rules
- Antitrust regulation
- Costs of environmental compliance.
- Carbon pricing mechanisms
These are potential limiting factors to long-term profitability.
Investment Implications
Technology
- The structural growth is preserved.
- The AI expenditure is multi-year.
- Importance of valuation discipline.
Preferred exposure: Nvidia, Microsoft, Apple.
Energy
- Pay attention to the durability of cash flow.
- The LNG and the integrated models are favored.
- Critical Dividend Sustainability.
Preferential exposure Shell, ExxonMobil (selective).
Conclusion
Q4 2025 profitability verified a growing performance disparity amid the technology and energy industries. AI-based infrastructure investment remains the driver of the earnings growth of the major tech-oriented companies, with energy companies being limited by pricing and regulation opportunities.
To the investors, there are three themes dominating:
- AI continues to be the main driving force of world profits.
- Diversification and capital restraint are the determinants of energy profitability.
- The valuation risks and geopolitical risks need to be selectively positioned.
Sustainable cash generation and structural growth exposure would continue to be at the center of the long-term returns as markets enter 2026.
Reference Links

Disclaimer:
This article is for informational and educational purposes only and does not constitute financial, investment, trading, or legal advice. Always do your own research or consult a licensed advisor before making trading decisions.


